Europe does not want to depend on foreign technology in the new digital order
Brussels wants to build its own capabilities in semiconductors, cloud computing and artificial intelligence as it seeks greater technological sovereignty from the US and China
For years, Europe grew used to a contradiction that it is only now beginning to see as a risk: being one of the world’s foremost regulatory powers in the digital sphere while remaining dependent on others for much of the technology those rules were designed to govern. Over the past decade, Brussels has assembled an extensive legislative arsenal aimed at curbing the power of big tech, from the General Data Protection Regulation (GDPR) to the Digital Markets Act, the Digital Services Act and the AI Act. Yet while Europe was writing rules, the United States and China were building companies, data centers, chips, cloud platforms and artificial-intelligence models on a scale that no European firm has managed to match.
Artificial intelligence has blown that contradiction wide open. Technology is no longer merely a question of business competitiveness; it has become a matter of power. Cloud services, data centers, semiconductors, networks, software and computing capacity have become strategic infrastructure. Those who control them do not simply provide services; they can influence the decision-making of those who depend on them.
The scale of Europe’s dependence is captured by one particularly striking figure: 92% of Western data is stored on U.S.-owned infrastructure, according to an Oliver Wyman analysis of European digital sovereignty. The problem, therefore, is not simply that Europe uses applications or services developed elsewhere. A critical share of the information on which the Western economy runs is housed in infrastructure that Europe does not control.
The European Commission itself offers another measure of that dependence: the EU relies on non-EU countries for more than 80% of its digital products, services, infrastructure and intellectual property, according to data compiled by EU institutions and cited by the European Parliament in its January 2026 resolution on technological sovereignty. The figure helps explain why Brussels no longer sees technological dependence as merely a business issue, but increasingly as a strategic challenge.

The European Commission has accepted that diagnosis and is trying to change the model. The goal is not to push U.S. companies out of the European market or to build a digital fortress isolated from the United States and China. Instead, the idea gaining ground in Brussels is that Europe should have enough homegrown alternatives to be able to choose, negotiate and, if necessary, do without a foreign supplier in technologies it considers critical.


European Commission President Ursula von der Leyen summed it up on June 3, 2026, when she unveiled the European Technology Sovereignty Package: “We cannot afford to depend on others for the technologies that keep our hospitals running, our energy grids stable and our services secure.” She added: “This is about protecting our citizens, defending our interests and making our own choices.”
The package presented by Brussels on June 3 is the clearest expression yet of that shift. The Commission has put forward two new legislative proposals, the Chips Act 2.0 and the Cloud and AI Development Act, known as CADA, alongside a European open-source strategy and a roadmap for digitalization and artificial intelligence in the energy sector.
These measures have not yet become law. They are legislative proposals that must still make their way through the EU’s policymaking process. But they offer a clear indication of the direction Brussels wants European technology policy to take.

The picture is even more striking in the cloud-computing market. AWS, Microsoft Azure and Google Cloud, the three major U.S. hyperscalers, account for roughly 70% of the European cloud-infrastructure market, while European providers hold only about 15%.
In 2017, European cloud providers controlled around 29% of the market. Five years later, their share had fallen to 15%, where it has since remained largely stagnant.
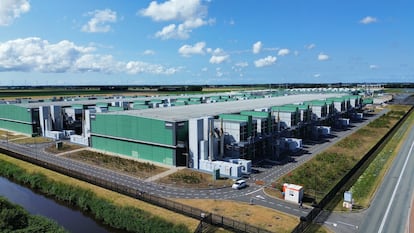
A hyperscaler is a technology giant that operates vast networks of data centers and provides computing power, storage and digital services on demand to other companies. Its influence also stems from the ecosystems it has built. A company may start by using a provider’s storage services and end up relying on the same vendor for databases, development tools, cybersecurity, data analytics and artificial intelligence.
That is where the concept of vendor lock-in comes into play: the phenomenon whereby customers become effectively tied to a particular technology platform. The more dependent a company becomes on a single provider, the more difficult and costly it is to switch. Europe has spent several years trying to tackle this problem through regulation. The Data Act, which began to apply in September 2025, includes measures designed to make it easier for customers to change providers of data-processing services, including cloud and edge-computing services. The regulation seeks to improve interoperability and portability while reducing the technical and financial barriers that make leaving a platform difficult.
The next step is the Digital Markets Act. In June 2026, the European Commission informed Amazon and Microsoft of its preliminary view that AWS and Azure should be designated as “gatekeepers” under the legislation. Brussels argues that the two companies are the EU’s leading cloud providers, with entrenched market positions, high switching costs and strong lock-in effects. The decision is not yet final, but it would extend the EU’s approach to regulating large digital platforms into the heart of cloud infrastructure. For Brussels, the cloud is no longer merely a market for IT services; it has become a strategic infrastructure.
The reason is artificial intelligence. Advanced AI models require enormous amounts of computing power. Training and running them depend on specialized processors, data centers, storage systems, high-speed networks and vast quantities of energy. AI is turning data centers into the factories that will produce much of the digital economy of the future.
The CADA project
That is why the Commission has designed the Cloud and AI Development Act (CADA). The proposal aims to at least triple the European Union’s data-center capacity over the next five to seven years, speed up and simplify permitting procedures for new facilities, improve access to energy, land, water and financing, and ensure sufficient computing capacity to support the expansion of artificial intelligence and cloud services. It also introduces a common European framework for assessing cloud and AI sovereignty and would allow public authorities to use that framework when making procurement decisions.
The most innovative aspect of CADA is precisely its definition of sovereignty. Brussels wants to move beyond the idea that a cloud service is sovereign simply because the data are physically stored within the European Union. The proposed framework establishes four levels of sovereignty. The first requires that data be processed and stored on infrastructure located in the EU. The second adds independence from third countries and transparency regarding the software supply chain. The third requires that the provider be owned and controlled from within the EU. The fourth, and highest, level demands full transparency and control over the software supply chain, as well as freedom from interference by third countries.
The distinction matters because a server may be located in Madrid while control remains in Seattle. That is precisely the concern that Sebastián Muriel, Telefónica’s chief digital officer, has brought into the European debate. In an article published in the business daily Cinco Días on May 23, titled Europe, Wake Up: Digital Sovereignty Cannot Be Built by Signing Lease Agreements, he argued that “believing sovereignty consists merely of hosting data on European soil is clearly insufficient.”
Muriel pointed out that the U.S. Cloud Act may allow U.S. authorities to request information from companies subject to U.S. jurisdiction even when the data are physically stored outside the country. “It makes no difference whether the server is in Madrid, Frankfurt or Dublin if the parent company is in Redmond or Mountain View,” he wrote. He also coined one of the phrases that best captures the issue: “We are encouraging a situation in which sovereignty becomes little more than a label stuck on a rental contract.”
That notion of “rented sovereignty” has become a guiding theme of Europe’s new strategy. The objective is not to stop using U.S. technology, but to avoid becoming irrevocably dependent on it. Strategic autonomy does not mean absolute independence but having enough homegrown capacity so that dependence does not turn into a vulnerability.
The Commission is trying to apply that logic to semiconductors. The Chips Act 2.0 starts from the premise that Europe accounts for just under 10% of global semiconductor production, according to a Polytechnique Insights analysis of the European semiconductor industry. The new proposal aims to strengthen European capabilities, develop cutting-edge technologies, increase the resilience of the supply chain and stimulate domestic demand for chips produced in Europe.

The goal is not for Europe to manufacture every chip it needs. That would be unrealistic. Rather, Brussels is seeking to ensure Europe does not lose industrial capacities that could become critical if the global supply chain breaks down. The pandemic, U.S.-China trade tensions and restrictions on certain technological components have shown that a seemingly efficient supply chain can quickly become a source of vulnerability.
The third pillar of the package is open-source software. The Commission intends to strengthen open alternatives across technology layers and promote their use in public administrations. The reasoning is that the more a government depends on proprietary software controlled by an external provider, the greater its technological dependence. Open source does not by itself guarantee sovereignty, but it can increase European control.
The fourth piece is energy. The Commission has recognized that it cannot support a massive expansion of data centers without addressing where the electricity to power them will come from. Its roadmap for digitalization and AI in the energy sector seeks to integrate data centers into Europe’s energy system and coordinate the growth of computing capacity with electricity availability and decarbonization goals. In this way, digital sovereignty is becoming increasingly tied to energy sovereignty.
Shortage of skilled workers
There is another less visible but decisive problem: 60% of EU companies report difficulties hiring qualified workers in fields such as artificial intelligence, cybersecurity and clean technologies, according to the European Parliament. The shortage of professionals has thus become another bottleneck for technological sovereignty: even if Europe has data centers, capital and companies, it needs engineers, AI specialists and cybersecurity experts able to make that ecosystem work.
Henna Virkkunen, executive vice president of the Commission responsible for Technological Sovereignty, Security and Democracy, framed the problem from a geopolitical perspective: “We are living through a global digital revolution and a worldwide race to shape the future of artificial intelligence. Europe must not be content to participate in this transformation; it must lead it.”
The shift in tone is unmistakable. Brussels is no longer focused solely on ensuring that big tech companies comply with European rules. It also wants European firms capable of developing technologies that can compete with them.
Europe’s investment effort still lags behind that of its main rivals. The European Union spent €381.4 billion on research and development, equivalent to 2.22% of GDP, according to the European Commission’s State of the Digital Decade 2025 report. Even so, that level of investment remains well below that of the United States and China. The Commission’s analysis estimates that Europe’s effort is 34% lower than the combined investment of the two powers.
The consequences of that investment gap, and of Europe’s difficulty in turning innovation into globally scaled businesses, are reflected in its corporate landscape. Only four of the world’s 50 largest technology companies are European, a statistic economist Mario Draghi highlighted in his assessment of the continent’s competitiveness. And the picture becomes even starker when viewed more broadly. According to PwC’s Global Top 100 Companies 2026 report, not a single European company ranks among the world’s 10 largest technology firms by market capitalization.
The AI gap
The gap is even more evident in artificial intelligence. In July 2026, the highest-ranked European AI model stood in 89th place in Artificial Analysis’s rankings. Every model above it came from either the United States or China. The statistic starkly captures the distance between Europe’s ambition to build its own AI industry and its current position in the global technology race.
Much of this diagnosis was set out by Draghi in his report on European competitiveness. Europe was not only losing ground in technology; it was also losing the ability to turn research into globally scaled companies. A year later, the former Italian prime minister put it even more bluntly: “Inaction threatens not only our competitiveness, but also our sovereignty.” The key word in his diagnosis is scale.
Europe has technology companies, but many are too small. Capital remains fragmented, and the European market is split across 27 national jurisdictions, tax systems and regulatory frameworks. The result is that Europe invents, but does not always scale. Draghi also noted that nearly 30% of the unicorns (a startup company valued at over $1 billion) created in Europe had subsequently moved their headquarters abroad.
That is the problem Brussels is now trying to address: not simply creating technology, but ensuring that technology developed in Europe stays in Europe, secures financing and grows into an industry. This is why public procurement has become increasingly important. In April, the European Commission awarded contracts worth up to €180 million for sovereign cloud services for EU institutions. The move cannot match the scale of investment made by U.S. hyperscalers, but it can help turn the public sector into an anchor customer for European providers.
Nor does the issue end with cloud computing or data centers. According to a GSMA Intelligence study published in May 2026, Europe will need €475 billion in investment in mobile networks by 2035 to complete its 5G rollout and regain digital leadership. Under current conditions, European operators are expected to mobilize only about €270 billion, leaving an investment gap of €205 billion. The figures matter because data centers and artificial intelligence cannot function independently of the networks that connect businesses, users and infrastructure.
The Financial Times examined this shift in an article by Barbara Moens published in late May. The piece described Europe’s move away from a strategy primarily focused on regulating large technology companies toward one aimed at fostering European alternatives in semiconductors, cloud computing and artificial intelligence. Moens summed up the objective with a telling phrase: Europe must “reclaim its place in the global race for geoeconomic power.”
Because digital sovereignty is no longer just a question of privacy. It is about who controls the data, the chips, the computing power, the networks and the critical infrastructure on which modern economies depend. And Europe is beginning to understand that legislation alone cannot guarantee any of those things. It needs companies, scale and investment, and above all European firms capable of becoming key players in that infrastructure.
Sign up for our weekly newsletter to get more English-language news coverage from EL PAÍS USA Edition