Middle East conflicts push Europe toward a second energy crisis in five years
Hormuz, Bab al-Mandab and the shutdown of the Saudi East-West pipeline, capped by damage to Russian refineries, trigger the biggest price surge since 2022

Donald Trump returned to power in Washington with two major foreign policy promises: to end the war in Ukraine “in 24 hours” and to keep his country out of more “forever wars.” Almost two years after his decisive electoral victory, the Russian invasion continues with no sign of a quick end, and the United States has plunged itself into yet another hornet’s nest in the Middle East. Two conflicts of unpredictable outcome have pushed fossil fuel costs to historic highs worldwide and are increasing doubts about whether — with price signals distorted — supply chains will withstand the pressure.
The relentless chain of setbacks is scarcely matched in recent memory. Through the Strait of Hormuz — the unavoidable exit route for oil and gas from the Persian Gulf — only a handful of ships now sail each day, either at their own risk or escorted by the U.S. Navy; a tiny fraction of the traffic that passed through that key waterway before the first strikes on Iran earlier this year.
Saudi Arabia, the world’s largest crude exporter, was put largely out of action for more than a week: attacks by pro-Iran militias forced the East-West pipeline, its only alternative to Hormuz, to shut down, although Reuters reported on September 24 that operations on the pipeline had resumed, with tankers awaiting loading. The Houthi rebels, always dependent on Tehran, are expanding their control over Bab al-Mandab, another crucial maritime passageway. And Russia, with its refineries severely damaged by Ukrainian drone strikes, is about to extend its ban on diesel exports for another month: supplying its domestic market is now almost a pipe dream. A quartet of adverse factors that, in short, leaves the world on the brink of another energy crisis.
“The situation has deteriorated a lot in the past two weeks [since the Houthis took control of the Bab al-Mandab Strait and following the attacks on the Saudi pipeline]. What we are seeing is unprecedented,” Francisco Blanch, global head of commodities and derivatives at Bank of America, tells EL PAÍS by phone. “The disorder in the Middle East is extreme, and there is neither enough crude on the market or, above all, enough refineries available to process it.”
If the main bottleneck in spring was jet fuel, now — mirroring what happened in the early months of Russia’s invasion of Ukraine — concerns center on diesel. Moscow, a historic European supplier, has nearly half of its refining capacity offline. Riyadh has effectively disappeared from the market: with three key facilities operating below capacity — the Yanbu, Samref and Yasref refineries, all on a Red Sea now turned into a tinderbox — it has been forced to pause all crude and fuel shipments to Europe.
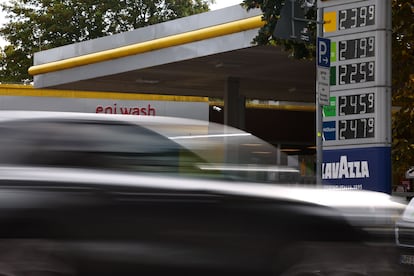
“Neither diesel nor heating oil have much of a short-term solution,” Blanch says. And what prices are signaling, with the gallon above $6 in the U.S. and the liter over €2 in most of the EU, is a “major” potential supply problem on the horizon “if supply chains have not been restored by Christmas.”
Could the world slide into a second major energy shock in less than five years? “Definitely,” Thierry Bros, a professor at Sciences Po Paris, replies on the phone. “Especially Europe, because of its external dependence and because fuel subsidies continue to delay electrification. Since we don’t have gas or oil, our only exit is to diversify and to destroy demand.”
In the words of the Bank of America analyst, “very difficult weeks” lie ahead. And there’s one major unknown: what will happen after the U.S. midterm elections on November 3, in which polls point to a historic reverse for the Republican Party, which may even lose both houses of Congress. “The big question is how Trump will react and whether or not that might open the door to diplomacy.”
Far from being isolated compartments, diesel, gasoline and kerosene are largely interconnected. Refineries — especially the most modern and flexible ones — can choose to produce more of one product at the expense of others. And that is exactly what has been happening for several months: facilities that favored jet fuel are now prioritizing diesel. The result: everything is much more expensive and there is a shared feeling among all analysts consulted that, despite prices already soaring, they do not fully reflect the severity of the situation.
There is, Blanch says, one factor that could “make things even worse”: Trump banning U.S. fossil fuel exports. “U.S. consumers might benefit from lower prices, but it would do great harm to the U.S. economy, which is currently being heavily supported by those sales,” he notes. The impact of such a potential veto, Eurasia Group analysts Gregory Brew and Henning Gloystein write in a recent client note, would be particularly severe in two regions: Europe and Latin America — by far the most dependent on U.S.-sourced fuels. Still, Samantha Gross of the Brookings Institution suspects that “real shortages may hit countries that cannot afford to pay much more for fuels.”
If a full-blown energy crisis has not yet arrived it is only thanks to four mitigating factors with few historical precedents. First, the world market was awash in oil before the Trump-Netanyahu duo launched the first strikes on Iran: supply exceeded demand, a structural imbalance that will widen. Second, the increasingly necessary electrification is reducing — and will reduce further — demand for gasoline and diesel. Third, strategic reserves were full; that is no longer the case after their rapid use in the initial stages of the closure of Hormuz. Fourth, the global economy depends far less on oil and its derivatives than ever before, which significantly lightens the burden of high prices.
And then there is gas. The true Gordian knot in Europe’s 2022–23 energy crisis now seems overshadowed by an oil shock that engulfs everything. But there are reasons to stay alert here too: the closure of Hormuz has sidelined the world’s second-largest exporter of liquefied natural gas (LNG), Qatar, which has been forced to cancel the bulk of its sales to the EU and Asia citing “force majeure.”
Continental reserves of LNG, key for industry and heating, are at their lowest in more than a decade and about 20 percentage points below where they usually stand at this time of year. “What we hope is that this winter, like the last, is not too cold in Europe. Because if it is, we could have serious problems,” says Ana Maria Jaller-Makarewicz, an analyst at the Institute for Energy Economics and Financial Analysis (IEEFA).
Unlike 2022 and 2023, when Russia’s invasion of Ukraine suddenly spiked prices and fears of shortages, we are, the IEEFA analyst sketches, “facing a slow-motion crisis.” Qatar is absent from the market. Flows from Norway are near their limit. And competition with Asia for LNG is much greater than a few months ago. Today’s prices of over €70 per megawatt hour have raised electricity costs, but they pale compared with the over €300 of four years ago. “Europe will have to pay more to attract LNG carriers originally destined for other parts of the world,” Gross predicts by email. “Uncertainty is enormous: the only clear thing is that there is no clear solution in sight,” Jaller-Makarewicz concludes.
Sign up for our weekly newsletter to get more English-language news coverage from EL PAÍS USA Edition